dollars image

1-Year CD Rates from Online Banks 2026

1-Year CD Rates from Online Banks 2026

Recent Articles


CD Rates on Upswing While Savings Rates Still Falling

Rate information contained on this page may have changed. Please find latest cd rates.

The latest batch of data shows that longer-term CD rate averages are moving up while shorter term CDs as well as savings and money market rates continue to fall. Are we near a bottom?

The latest batch of data shows that longer-term CD rate averages are moving up while shorter term CDs as well as savings and money market rates continue to fall. Are we near a bottom?

The chart below shows the rate trends and the uptick in 3-year and 5-year rates over the last two weeks based on the average rates from the BestCashCow rate tables.

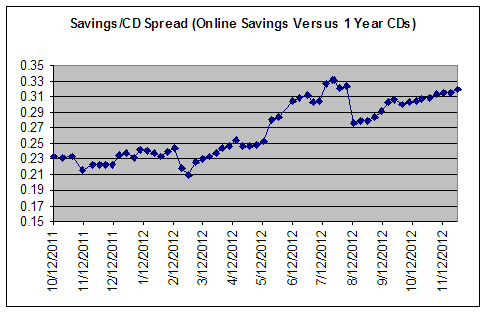
The spread, or the difference between the average savings/money market rate and the avarage 3 year CD rate is now at its highest point in over a year. My interpretation is that with rising inflation expectations, banks have to pay consumers more to lock their money up for longer periods of time. Banks can cut short term rates because investors have less places to put the cash that they wish to keep liquid. But if the economy revs up, or inflation rears its head, look for short term rates to begin to rise.

While it's impossible to know for sure, the spread may be an indicator that we have already reached and passed the bottom in longer-term deposit rates and are rapidly approaching that point with savings, money markets and short-term CDs. It may also indicate, as I speculated before the latest stock market rally, that it may be a positive indicator for the general economy and financial markets.


Longer-term CD Rates on Rise - Weekly Rate Update

Rate information contained on this page may have changed. Please find latest cd rates.

Rates on Certificate of Deposits rose in the last two weeks, and the average 5 year CD rate according to the BestCashCow rate table is now at its highest since August 2009. The average for the 5 year CD has risen from 3.24% APY to 3.42% APY. Are we seeing more sparks of life? It would certainly take more yield to convince me to lock my money up for five years, especially if the economy is reviving. Perhaps this sentiment is gaining steam.

The Dow hit 10,000 this week as markets topped their 52 week high. I've been surprised that the market has continued to go up in the face of mounting forecolosures and continued losses in the banking sector (Bank of America, Citi). Unemployment also continues its inexorable rise although the pundits have conditioned us to believe that it's a lagging indicator and shouldn't impact the economic recovery.

And one question that remains unanswered for me is this. If the US economy is 75% consumer driven, and consumers are tapped out, what is driving this stock recovery? If anyone knows, please tell me.

Economic indicators do point to a recovery, or at least a thawing inthe recession. Iinflation actually increased month-over-month in September, rising .2% versus .1% in August. Still, neither reading is going to get me running for the hills to panhandle for gold. In an article on the inflation readings, Sam Cass made the point that in the past two downturns, low inflation persisted well into the recovery. Indeed, the spike in prices that occurred once the economy recovered was mainly a spike in asset prices - stocks, real estate, bonds, etc. Income and other items measured by the CPI never really showed much of an increase. That's what allowed the Fed to keep rates low and feed each of the investment bubbles. Even the spike in oil in 2008 was due to trading and speculation as opposed to fundamentals.

CD and Savings Rates

So, how does this translate into savings and CD rates? Rates on Certificate of Deposits rose in the last two weeks, and the average 5 year CD rate according to the BestCashCow rate table is now at its highest since August 2009. The average for the 5 year CD has risen from 3.24% APY to 3.42% APY. Are we seeing more sparks of life? It would certainly take more yield to convince me to lock my money up for five years, especially if the economy is reviving. Perhaps this sentiment is gaining steam.

Savings rates continue their very slow drift down although the pace of descent should really be described as glacial. In the last 8 weeks, the average savings account rate has dropped by only 8 basis points from 1.80% APY to 1.72% APY. For all intensive purposes, savings rates have bottomed and are now waiting for the Fed to raise rates to begin climbing. That may not happen for some time.

Looking at the yield curve we have developed for deposit accounts we can see that the spread between savings rates and 36-month CDs reached a new high last week. This reflects the rise in longer term CD rates even as savings rates continue their glacial descent. The yield curve is steepening which is normally a sign of economic recovery and expansion.


Difference Between 5-Year and 1-Year CD Rates Hits High - Weekly Rate Update

Rate information contained on this page may have changed. Please find latest cd rates.

Most savings and CD rates hit record lows last week, except for the 5-year CD, which continued to show gains in yield. Average savings rates reached a new record low of 1.46% APY, down 1 basis point from 1.47% APY the previous week. Average one-year cd rates fell 3 basis points to 1.82% APY. Average three-year cd rates dropped two basis points to 2.61% APY.

There were several reports over the past week which seemed to indicate that the economy has stabilized and maybe even turned the corner. The latest GDP figures showed that the economy grew by 5.7% in the fourth quarter of 2009, above economists expectations. In addition, the unemployment rate in January dipped below 10%.
Is this cause to celebrate? Not yet, but it's reason to be optimistic. An end to things getting worse is the necessary prelude to things getting better.

Despite all of this, if you look at the Federal Funds Rate predictions chart (below), you can see that markets do not anticipate a rate increase through the June Fed meeting. I suspect the rate will stay pegged at 0-25% a good deal longer, and potentially through the rest of 2010.

A low Fed Funds Future rate means low rates on savings accounts, money markets, and certificates of deposit.

CD and Savings Rates

Most savings and CD rates hit record lows last week, except for the 5-year CD, which continued to show gains in yield. Average savings rates reached a new record low of 1.46% APY, down 1 basis point from 1.47% APY the previous week. Average one-year cd rates fell 3 basis points to 1.82% APY. Average three-year cd rates dropped two basis points to 2.61% APY.

The only glimmer of good news were five-year CD rates which for the second week in a row rose, moving from 3.20% APY to 3.29% APY.

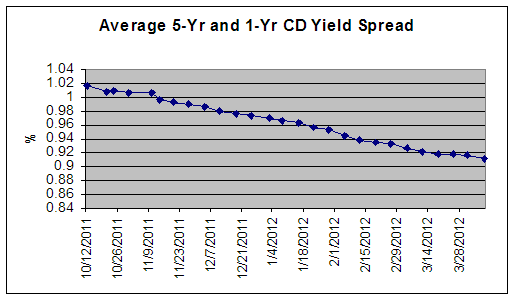
This week I've expanded the spread analysis I've done in the past to include the ratio of 5-year average CD rates to 1-year average CD rates. The chart also continues to track the ratio of average 3-year CD rates to the average savings rate, as reported by the BestCashCow rate tables.

As you can see, both the cd spread and the savings/cd spread are near record highs. What does that mean? It means as a depositor, you are being compensated more highly for putting your money into a longer-term deposit account then you were even a year ago. This isn't a suprise as savings rates have collapsed while longer-term CD rates have come down much more gradually.

The ratio also leads to an interesting question. At what point should an investor consider opening a 2-5 year CD? You can now earn 1.5 percentage points more by opening a 5 year CD versus a 1-year CD. If interest rates stay low for the next couple of years, as is possible, then perhaps this elevated spread makes opening the account worth it.

Next week, I'll model the different scenarios to try and develop a better understanding under what scenarios it will make sense to open a longer-term CD.

Regardless of this analysis, CD laddering may be a good way to smooth out the return you receive from your CD portfolio. Several banks have come out with breakable CDs, that allow users to withdraw money penalty free, and still other banks are lowering the withdrawal penalty for removing money before maturity.